How Do I Get Out Of A Car Loan

Picture this: You’re cruising down the highway, windows down, your favorite playlist blasting, when suddenly the thought hits—what if I could just… not owe this car anymore? N...

Picture this: You’re cruising down the highway, windows down, your favorite playlist blasting, when suddenly the thought hits—what if I could just… not owe this car anymore? No more monthly payments, no more stressing over interest rates, just pure, unadulterated freedom. Sounds like a fantasy, right? Well, not quite. There are actually a few sneaky (but totally legal) ways to ditch that car loan faster than you can say "Uber surge pricing."
First things first: paying it off early is the most straightforward route. Most lenders will let you pay extra toward your principal whenever you want—no penalties, no guilt trips. Think of it like leveling up in a video game: every extra payment is a new achievement unlocked. Just check your loan agreement to confirm there are no prepayment fees lurking in the fine print.
Refinance Like a Pro
If your current loan has a higher interest rate than you’d get today, refinancing could be your golden ticket. Imagine swapping a 5% interest rate for a 2.9%—that’s like finding a $20 bill in your jeans pocket every month. Websites like Credit Karma or Bankrate make comparing lenders easier than scrolling through TikTok for the next viral dance.
Must Read
Pro tip: If you’ve got stellar credit, you might even snag a 0% APR balance transfer card. It’s like getting a free ride on the highway—just move your loan balance to a new card with no interest for a limited time. Just make sure you can pay it off before the promo period ends, or you’ll be back to square one.
Sell the Car (But Not Too Soon)
If you’re ready to trade in your ride for something newer (or just something that doesn’t haunt your dreams), selling it could knock out your loan faster. But here’s the catch: don’t sell until you’ve paid off at least 50% of the loan. Otherwise, you’ll be stuck with a "gap" between the car’s value and what you owe—like trying to fit a square peg into a round hole.
List it on Craigslist or Facebook Marketplace for top dollar, or trade it in at a dealership. Either way, use the proceeds to pay down your loan aggressively. It’s like paying off a credit card debt—once it’s gone, you’ll feel lighter than a feather.
Side Hustle Your Way Free
Can’t refinance? No problem. Just throw some extra cash at it. Start a side hustle—think gig work, freelancing, or even selling old clothes on Poshmark. Every extra $100 you toss at your loan is like deflating the balloon of debt just a little bit more.
 Car Loan After Repossession: Complete Recovery Guide | ASAP Credit
Fun fact: If you put an extra $200 a month toward a $20,000 loan at 5% interest, you’ll save over $1,000 in interest and pay it off almost a year early. That’s like getting a free vacation—without the jet lag.
The "Snowball" Method (Because Who Doesn’t Love a Good Snowball Fight?)
If you’ve got multiple debts, try the debt snowball method: Pay off the smallest loan first, then roll that payment into the next one. It’s like dominoes—once the first one falls, the rest follow. The psychological win of knocking out a loan early keeps you motivated, like finally beating that one level in a game you’ve been stuck on.
Just don’t confuse this with the debt avalanche method, which targets the highest-interest debt first. It’s like choosing between a slow burn (avalanche) and a quick victory (snowball)—pick what keeps you up at night.
Negotiate Like a Boss
If you’re struggling to make payments, don’t be afraid to pick up the phone and talk to your lender. They’d rather work with you than watch you default. Some might lower your interest rate, extend the term, or even pause payments temporarily. It’s like calling customer service—except this time, you’re the one in charge.
Pro move: If you’ve been a loyal customer, mention it. Lenders love loyalty—kind of like how your favorite coffee shop remembers your order. A little charm never hurt anyone.
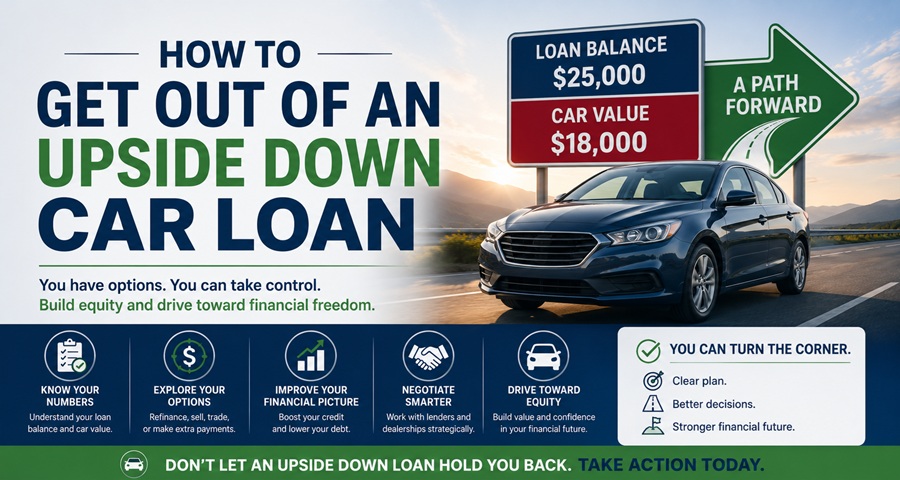 How to Get Out of an Upside Down Car Loan: Strategies That Work
What If You Just… Stop Paying?
Okay, hear us out: technically, you can stop paying, but let’s just say that’s the financial equivalent of quitting a gym membership and then pretending you’re still in shape. Your credit score will take a nosedive, and you’ll owe way more in late fees and penalties. It’s like skipping leg day—you’ll regret it later.
Instead, consider debt settlement—where you negotiate a lump-sum payoff for less than you owe. It’s risky, but if you’re drowning, it might be worth a shot. Just know that this will destroy your credit for years, so only do it as a last resort.
Why This Matters (Beyond Just the Car Loan)
Getting out from under a car loan isn’t just about freeing up cash—it’s about mental space. That monthly payment is like a tiny, persistent voice in your head, whispering, "You still owe me." Once it’s gone, you’ll feel like you’ve uninstalled an app you never wanted—no notifications, no reminders, just peace.
Think of it this way: Every dollar you put toward debt is a dollar you could be using for travel, hobbies, or even just a fancy coffee. Life’s too short to be tied down by something that’s already paid for—unless, of course, you’re into that whole "car payment lifestyle" thing. (We won’t judge.)
At the end of the day, financial freedom isn’t about being perfect—it’s about making small, smart moves that add up. Whether you refinance, sell the car, or just throw extra cash at it, every step forward is a win. And who knows? Maybe one day, you’ll look back and realize you didn’t just pay off a loan—you paid yourself.
